HR9481Referred to Committee
RETURN Act
Introduced
In Committee
3
Passed One Chamber4
Passed Both5
Signed into Law119th
Congress
2026-06-25
Introduced
5
Cosponsors
HR
ⓘType
Sponsor
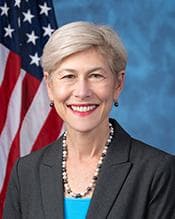
Deborah K. Ross
Democrat · NC · Representative
Votes with party: 99.0% (671 recorded votes)
Top industries funding sponsor:
- Progressive Groups$78k
- Climate & Environment$1k
Full profile: /officials/R000305
Source: Congress.gov · FEC
Cosponsors (5)
Members who have signed on to support this bill since introduction. Source: Congress.gov.
Latest Action
The most recent step in the bill's legislative path. Committee Activity below shows referrals and reports; the full action-by-action history including floor proceedings lives at Congress.gov →
Committee Activity
Currently in
- House Committee on Ways and MeansReferred To · 2026-06-25
Plain-English Summary
The proposal would change how the IRS handles requests from taxpayers who believe they overpaid their taxes and deserve money back. It aims to speed up the process for reviewing these refund claims and improve how the IRS responds to people seeking their money, potentially reducing wait times and making it easier for taxpayers to get answers about their cases.
AI-assisted summary generated from the official bill metadata (title, subjects, actions) sourced from Congress.gov. Cached and reviewed. Always verify against the official text linked below.
Subjects
Taxation
Full Bill Text
Verbatim text published on Congress.gov via GovInfo. Use Cmd+F / Ctrl+F to search within this excerpt.
[Congressional Bills 119th Congress] [From the U.S. Government Publishing Office] [H.R. 9481 Introduced in House (IH)] <DOC> 119th CONGRESS 2d Session H. R. 9481 To amend the Internal Revenue Code of 1986 to improve responses by the Internal Revenue Service to claims for refund, and for other purposes. _______________________________________________________________________ IN THE HOUSE OF REPRESENTATIVES June 25, 2026 Ms. Ross (for herself, Mr. Panetta, and Ms. DeLauro) introduced the following bill; which was referred to the Committee on Ways and Means _______________________________________________________________________ A BILL To amend the Internal Revenue Code of 1986 to improve responses by the Internal Revenue Service to claims for refund, and for other purposes. Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled, SECTION 1. SHORT TITLE. This Act may be cited as the ``Restoring Efficiency in Taxpayer Updates, Refunds, and Notifications Act'' or the ``RETURN Act''. SEC. 2. RESPONSES TO CLAIMS FOR REFUND REQUIRED. (a) In General.--Subsection (l) of section 6402 of the Internal Revenue Code of 1986 is amended to read as follows: ``(l) Explanation of Reason for Refund Disallowance.-- ``(1) In general.--Not later than the applicable date, the Secretary shall review any claim for refund, make a determination with respect to such claim, and, in the case of a disallowance of such claim (in whole or in part), provide the taxpayer with a detailed written explanation for such disallowance, which shall-- ``(A) be mailed to the last known address of the taxpayer, and ``(B) in the case of any taxpayer entitled to an appeal of such determination, include instructions for appealing such disallowance to the Internal Revenue Service Independent Office of Appeals. ``(2) Failure to make timely determination.-- ``(A) In general.--In the case of any claim for refund for which the Secretary fails to satisfy the requirements of paragraph (1) by the applicable date, for purposes of determining interest on any overpayment for any period subsequent to such date, the overpayment rate (as established under section 6621(a)(1)) shall be increased by 1 percentage point. ``(B) Limitation.--With respect to any claim for refund described in subparagraph (A), the amount of any increase in interest on any overpayment pursuant to such subparagraph shall not exceed $500. ``(C) Adjustment for inflation.-- ``(i) In general.--In the case of any claim for refund filed during any calendar year beginning after 2026, the $500 amount in subparagraph (B) shall be increased by an amount equal to-- ``(I) such dollar amount, multiplied by ``(II) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year, determined by substituting `calendar year 2024' for `calendar year 2016' in subparagraph (A)(ii) thereof. ``(ii) Rounding.--If any amount determined under clause (i) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50. ``(3) Frivolous claims.-- ``(A) In general.--In the case of any frivolous claim-- ``(i) paragraph (1) shall not apply, and ``(ii) not later than the applicable date, written notification of the denial of such claim shall be mailed to the last known address of the taxpayer. ``(B) Definition.--For purposes of this paragraph, the term `frivolous claim' means a claim for refund which is based on a position which-- ``(i) a Federal court has determined to be frivolous, and ``(ii) the Secretary has identified as frivolous for purposes of subsection (c) of section 6702. ``(4) Applicable date.--For purposes of this subsection, the term `applicable date' means, with respect to any claim for refund-- ``(A) the date which is 12 months after the date of receipt of such claim by the Secretary, or ``(B) such other date as is agreed…
Show the remaining 39 wordsHide the remaining 39 words
to by the Secretary and the taxpayer.''. (b) Effective Date.--The amendment made by this section shall apply to any claim for refund received after the date which is 12 months after the date of enactment of this Act. <all>
Related legislation
Bills by the same sponsor or covering overlapping subjects.
- HR10599No Surprise Bills for Seniors ActReferred to Committee · 2026-09-24
- HR10525Tropospheric Ozone Research Act of 2026Referred to Committee · 2026-09-21
- HR10037Virtual-Based Opioid Treatment for Veterans ActReferred to Committee · 2026-08-10
- HR9971Advancing International and Foreign Language Education ActReferred to Committee · 2026-07-27