S5616Referred to Committee
ADAPT Act
Introduced
In Committee
3
Passed One Chamber4
Passed Both5
Signed into Law119th
Congress
2026-09-30
Introduced
3
Cosponsors
S
ⓘType
Sponsor
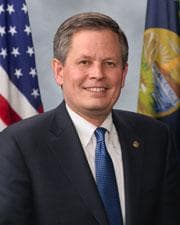
Steve Daines
Republican · MT · Senator
Votes with party: 77.4% (889 recorded votes)
Full profile: /officials/D000618
Source: Congress.gov · FEC
Cosponsors (3)
Members who have signed on to support this bill since introduction. Source: Congress.gov.
Latest Action
The most recent step in the bill's legislative path. Committee Activity below shows referrals and reports; the full action-by-action history including floor proceedings lives at Congress.gov →
Committee Activity
Currently in
- Senate Committee on FinanceReferred To · 2026-09-30
Plain-English Summary
Plain-English summary pending. Introduced on 2026-09-30. Check back soon — summaries are generated as bills progress through Congress.
Full Bill Text
Verbatim text published on Congress.gov via GovInfo. Use Cmd+F / Ctrl+F to search within this excerpt.
[Congressional Bills 119th Congress] [From the U.S. Government Publishing Office] [S. 5616 Introduced in Senate (IS)] <DOC> 119th CONGRESS 2d Session S. 5616 To amend the Internal Revenue Code of 1986 to reform the treatment of digital assets. _______________________________________________________________________ IN THE SENATE OF THE UNITED STATES September 30, 2026 Mr. Daines (for himself, Ms. Lummis, Mr. Moreno, and Mr. Scott of South Carolina) introduced the following bill; which was read twice and referred to the Committee on Finance _______________________________________________________________________ A BILL To amend the Internal Revenue Code of 1986 to reform the treatment of digital assets. Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled, SECTION 1. SHORT TITLE; ETC. (a) Short Title.--This Act may be cited as the ``Aligning Digital Assets with Principles of Taxation Act'' or the ``ADAPT Act''. (b) Table of Contents.--The table of contents of this Act is as follows: Sec. 1. Short title; etc. Sec. 2. Nonrecognition of gain or loss on certain sales, exchanges, or dispositions of stablecoins. Sec. 3. Mark to market election. Sec. 4. Source rules for digital asset validation activities. Sec. 5. Certain trading in digital assets not treated as a trade or business within the United States. Sec. 6. Transfer of digital assets under certain agreements. Sec. 7. Application of wash sale rules to digital assets. Sec. 8. Treatment of trusts and publicly traded partnerships holding digital assets. Sec. 9. Application of constructive sale rules to digital assets. Sec. 10. Charitable contributions of widely traded digital assets. Sec. 11. Treatment of de minimis digital asset network fees. Sec. 12. Treatment of income from qualified digital asset validation activity by tax-exempt entities. Sec. 13. Application of registration-required obligation rules. Sec. 14. Treatment of certain foreign entities established in connection with decentralized autonomous organizations. Sec. 15. Definitions. SEC. 2. NONRECOGNITION OF GAIN OR LOSS ON CERTAIN SALES, EXCHANGES, OR DISPOSITIONS OF STABLECOINS. (a) In General.--Part III of subchapter O of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after section 1033 the following new section: ``SEC. 1034. CERTAIN SALES, EXCHANGES, OR DISPOSITIONS OF STABLECOINS. ``(a) In General.--No gain or loss shall be recognized on the sale, exchange, or disposition of covered payment stablecoins to purchase products or services. ``(b) Definitions.-- ``(1) Covered payment stablecoin.--The term `covered payment stablecoin' means a qualified U.S. dollar stablecoin which-- ``(A) was identified in the most recent report published by the Secretary under paragraph (2) before the sale, exchange, or disposition of such stablecoin, and ``(B) was acquired by the taxpayer at a price within 3 percent of $1.00. ``(2) Identification by treasury.--Not less frequently than every 3 months, the Secretary shall make publicly available a report identifying each qualified U.S. dollar stablecoin that, during the 12-month period ending on the last day of the preceding month, was actively traded at a price within 3 percent of $1.00. ``(c) Exclusions.-- ``(1) Trade or business.--Subsection (a) shall not apply to the sale, exchange, or disposition of a covered payment stablecoin by-- ``(A) a trader, broker, or dealer in qualified U.S. dollar stablecoins, or ``(B) to the extent provided by the Secretary, any person in a trade or business which is substantially similar to a trade or business described in subparagraph (A). ``(2) Functional currency other than u.s. dollar.-- Subsection (a) shall not apply to any taxpayer or qualified business unit (as defined in section 989(a)) that uses a functional currency (as defined in section 985(b)) other than the dollar. ``(d) Books and Records.--In such form and manner as the Secretary may prescribe, a…
Show the remaining 8,043 wordsHide the remaining 8,043 words
taxpayer shall maintain books and records sufficient to distinguish sales, exchanges, or dispositions of covered payment stablecoins eligible for nonrecognition under subsection (a) from transactions which are not eligible under such subsection. ``(e) Regulations and Guidance.--The Secretary shall prescribe such regulations or other guidance as may be necessary or appropriate to carry out the purposes of this section, including-- ``(1) requirements relating to recordkeeping and broker information reporting, and ``(2) allocation of basis and characterization of the asset and any gain or loss.''. (b) Exemption From Information Reporting.--Section 6045 of such Code is amended by adding at the end the following new subsection: ``(i) Exemption for Certain Digital Asset Transactions.-- ``(1) Covered payment stablecoins.--In the case of the sale, exchange, or disposition of any covered payment stablecoin for which no gain or loss is recognized under section 1034(a), no return shall be required under subsection (a). ``(2) Regulations.--The Secretary shall prescribe such regulations or other guidance as may be necessary or appropriate to carry out this subsection, including rules under which a broker-- ``(A) may rely on information or certifications provided by a customer for purposes of determining whether any applicable requirements under section 1034 have been satisfied, ``(B) shall not be required to determine whether the requirement under section 1034(b)(1)(B) has been satisfied with respect to a qualified U.S. dollar stablecoin if the acquisition of such qualified U.S. dollar stablecoin was not effected by such broker, and ``(C) shall not be required to determine any fact that is not known or reasonably available to such broker.''. (c) Clerical Amendment.--The table of sections for part III of subchapter O of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 1033 the following new item: ``Sec. 1034. Certain sales, exchanges, or dispositions of stablecoins.''. (d) Effective Date.--The amendments made by this section shall apply with respect to transactions entered into after December 31, 2026. SEC. 3. MARK TO MARKET ELECTION. (a) In General.--Section 475 of the Internal Revenue Code of 1986 is amended-- (1) in subsection (d), by adding at the end the following new paragraphs: ``(4) Treatment of covered digital assets which are securities or commodities.--In the case of any covered digital asset which is a security or commodity (determined without regard to this paragraph), such covered digital asset shall not be treated as a security or commodity for purposes of subsections (b) through (g). ``(5) Adjustments attributable to mark to market treatment of securities, commodities, or covered digital assets.--In the case of an adjustment described in section 481(a) by reason of the application of subsection (a), (e), (f), or (g) of this section, the character of any income or loss with respect to any property as a result of such adjustment shall be the same as the character of the gain or loss which would have resulted from the sale of such property as of the close of the taxable year preceding the year of the change (within the meaning of section 481) under the method of accounting used for such preceding taxable year.'', (2) by redesignating subsection (g) as subsection (h), and (3) by inserting after subsection (f) the following new subsection: ``(g) Election of Mark to Market for Dealers and Traders in Covered Digital Assets.-- ``(1) Dealer in covered digital assets.--In the case of a dealer in covered digital assets who elects the application of this paragraph, this section shall apply to covered digital assets held by such dealer in the same manner as this section applies to securities held by a dealer in securities. ``(2) Trader in covered digital assets.--In the case of a person who is engaged in a trade or business as a trader in covered digital assets and who elects to have this paragraph apply to such trade or business as a trader in such assets, subsection (f)(1) shall apply to covered digital assets held by such trader in connection with such trade or business in the same manner as such subsection applies to securities held by a trader in securities. ``(3) Election and revocation.--An election under paragraph (1) or (2) may be made without the consent of the Secretary. An election, once made, shall apply to the taxable year for which made and all subsequent taxable years unless revoked with the consent of the Secretary. ``(4) Definitions.--For purposes of this subsection-- ``(A) Covered digital asset.--The term `covered digital asset' means-- ``(i) any traded digital asset, ``(ii) any qualified U.S. dollar stablecoin, ``(iii) any notional principal contract with respect to any traded digital asset, ``(iv) any evidence of an interest in, or derivative financial instrument in, any traded digital asset or any notional principal contract described in clause (iii), including any option, forward contract, futures contract, short position, or similar financial instrument, and ``(v) any position which-- ``(I) is not described in clause (i), (ii), (iii), or (iv), ``(II) is a hedge with respect to any item described in clause (i), (ii), (iii), or (iv), and ``(III) is clearly identified in the taxpayer's records as being described in this clause before the close of the day on which it was acquired or entered into (or such other time as the Secretary may by regulations prescribe). ``(B) Dealer in covered digital assets.--The term `dealer in covered digital assets' means a taxpayer which-- ``(i) regularly purchases covered digital assets from, or sells covered digital assets to, customers in the ordinary course of a trade or business, or ``(ii) regularly offers to enter into, assume, offset, assign, or otherwise terminate positions in covered digital assets with customers in the ordinary course of a trade or business. ``(5) Regulations and guidance.--The Secretary shall prescribe such regulations or other guidance as may be necessary or appropriate to carry out the purposes of this subsection, including rules to coordinate this subsection with the treatment under this section of a covered digital asset that is also a security or commodity.''. (b) Application to First Taxable Year.--In the case of any taxpayer who makes an election under paragraph (1) or (2) of subsection (g) of section 475 of the Internal Revenue Code of 1986 (as added by subsection (a)) with respect to the first taxable year beginning after the date of enactment of this Act-- (1) any identification required pursuant to the application of such subsection with respect to covered digital assets held on the first day of such taxable year shall be treated as timely made if made on or before the 30th day of such taxable year, and (2) the net amount of the adjustments required to be taken into account by the taxpayer under section 481 of such Code by reason of the application of such subsection shall be taken into account ratably over the 4-taxable year period beginning with such taxable year. (c) Treatment as Specified Service Trade or Business.--Section 199A(d)(2)(B) of the Internal Revenue Code of 1986 is amended by striking ``or commodities (as defined in section 475(e)(2))'' and inserting ``commodities (as defined in section 475(e)(2)), traded digital assets, or covered digital assets (as defined in section 475(g)(4)(A))''. (d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2026. SEC. 4. SOURCE RULES FOR DIGITAL ASSET VALIDATION ACTIVITIES. (a) In General.--Section 863 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection: ``(f) Special Rules for Income From Validation of Digital Assets.-- ``(1) In general.--Except as provided in paragraph (2) or in regulations, any income derived from digital asset validation supporting activities-- ``(A) if derived by a United States person, shall be sourced in the United States, and ``(B) if derived by a person other than a United States person, shall be sourced outside the United States. ``(2) Treatment of branches.-- ``(A) Foreign branches.--Except as provided in regulations, in the case of a United States person with a qualified business unit (as defined in section 989(a)) in a foreign country, income described in paragraph (1) that constitutes business profits attributable to such unit shall be sourced outside the United States. ``(B) U.S. branches.--Excepts as provided in regulations, in the case of a person that is not a United States person and that maintains an office or other fixed place of business in the United States, income described in paragraph (1) attributable to such office or other fixed place of business shall be sourced in the United States. ``(C) Attribution.--For purposes of subparagraphs (A) and (B), the Secretary shall issue such regulations or other guidance as the Secretary determines necessary or appropriate for purposes of determining the amount of business profits attributable to a qualified business unit or office or other fixed place of business. ``(3) Special rules for mining.-- ``(A) Certain amounts treated as income.--For purposes of paragraph (1)-- ``(i) In general.--Except as provided in clause (ii), any amounts received (including amounts received as digital assets or transaction fees) directly through a mining pool or similar arrangement as a result of the taxpayer's performance of, or contribution of computing power to, mining shall be treated as income derived from digital asset validation supporting activities. ``(ii) Exclusion.--Compensation received for providing services to another person for services related to mining (including hosting and equipment management services) shall not be treated as income derived from digital asset validation supporting activities. ``(B) Rules for attribution to branches.--The Secretary shall prescribe rules for the purposes of determining whether, and to what extent, income derived from mining is attributable to a qualified business unit or an office or other fixed place of business under paragraph (2). Such rules shall take into account-- ``(i) the location and relative contribution of the computing equipment used in the mining activity, ``(ii) the location of personnel performing functions with respect to the operation, management, or maintenance of such equipment, and ``(iii) such other functions, assets, risks, or other factors as the Secretary determines necessary or appropriate. ``(4) Treatment of partnerships.--In the case of a partnership, except as otherwise provided by the Secretary in regulations or other guidance, this subsection shall be applied at the partner level.''. (b) Effective Date.--The amendment made by this section shall apply to income derived after the date of the enactment of this Act. (c) No Inference.--The amendments made by this section shall not be construed to create any inference with respect to whether, or the time at which, a digital asset created, issued, acquired, or received in connection with digital asset validation activity (as defined in section 7701(q), as added by this Act) is includible in gross income. SEC. 5. CERTAIN TRADING IN DIGITAL ASSETS NOT TREATED AS A TRADE OR BUSINESS WITHIN THE UNITED STATES. (a) In General.--Section 864(b)(2) of the Internal Revenue Code of 1986 is amended by redesignating subparagraph (C) as subparagraph (D) and by inserting after subparagraph (B) the following new subparagraph: ``(C) Digital assets.-- ``(i) In general.--Trading in traded digital assets through a resident broker, commission agent, custodian, or other independent agent. ``(ii) Trading for taxpayer's own account.--Trading in traded digital assets for the taxpayer's own account, whether by the taxpayer or the taxpayer's employees or through a resident broker, commission agent, custodian, staking provider, or other agent, and whether or not any such employee or agent has discretionary authority to make decisions in effecting the transactions. This clause shall not apply in the case of a dealer in covered digital assets (as defined in section 475(g)(4)(B)).''. (b) Conforming Amendments.-- (1) Subparagraph (D) of section 864(b)(2) of such Code (as redesignated by subsection (a)) is amended-- (A) by striking ``subparagraphs (A)(i) and (B)(i)'' and inserting ``subparagraphs (A)(i), (B)(i), and (C)(i)'', and (B) by striking ``or in commodities'' and inserting ``in commodities, or in traded digital assets''. (2) The heading of section 864(b)(2) of such Code is amended by striking ``or Commodities'' and inserting ``, Commodities, or Digital Assets''. (c) Effective Date.-- (1) In general.--The amendments made by this section shall apply to taxable years beginning after December 31, 2026. (2) No inference.--The amendments made by this section shall not be construed to create any inference with respect to the application of section 864(b)(2) of the Internal Revenue Code of 1986 to the trading of digital assets for any period beginning before the date described in paragraph (1). SEC. 6. TRANSFER OF DIGITAL ASSETS UNDER CERTAIN AGREEMENTS. (a) Transfers Under Agreement.-- (1) In general.--Section 1058 of the Internal Revenue Code of 1986 is amended-- (A) in subsection (a), by striking ``securities (as defined in section 1236(c))'' and inserting ``applicable assets'', and (B) by adding at the end the following new subsection: ``(d) Applicable Asset.--For purposes of this section, the term `applicable asset' means-- ``(1) any security (as defined in section 1236(c)), and ``(2) traded digital assets.''. (2) Conforming amendments.-- (A) Subsections (a) and (b) of section 1058 of such Code, as amended by paragraph (1), are each amended by striking ``securities'' each place it appears and inserting ``applicable assets''. (B) The heading of section 1058 of such Code is amended by striking ``securities'' and inserting ``assets''. (C) The item relating to section 1058 in the table of sections for part IV of subchapter O of chapter 1 of such Code is amended by striking ``securities'' and inserting ``assets''. (b) Treatment of Certain Legal Entitlements and Obligations Which Accrue During Period of Agreement.--Section 1058(b)(2) of the Internal Revenue Code of 1986, as amended by subsection (a)(2), is amended by inserting ``(including, in the case of a traded digital asset, to the extent provided by the Secretary, amounts equivalent to any protocol distribution or staking reward with respect to such asset, or to any transaction fee, priority fee, or tip allocated to the owner by reason of staking)'' after ``and other distributions''. (c) Payments With Respect to Loans.-- (1) In general.--Section 512 of the Internal Revenue Code of 1986 is amended-- (A) in subsection (a)(5)(A), by striking ``in respect of a security (as defined in section 1236(c))'' and inserting ``in respect of an applicable asset (as defined in section 1058(d))'', and (B) in subsection (b)(5), by striking ``securities (as defined in section 1236(c))'' and inserting ``applicable assets (as defined in section 1058(d))''. (2) Inclusion of certain payments.--Section 512(a)(5)(A)(i) of such Code is amended by striking ``or other distributions'' and inserting ``property, legal entitlements, or other distributions''. (3) Conforming amendments.-- (A) Section 512 of such Code is amended by striking ``payments with respect to securities loans'' each place it appears in subsection (a)(5) and (b)(1) and inserting ``payments with respect to applicable asset loans''. (B) Section 512(a)(5) of such Code is amended-- (i) by striking ``the security'' each place it appears and inserting ``the applicable asset'', (ii) by striking ``securities'' each place it appears and inserting ``applicable assets'', and (iii) by striking ``securities loans'' in the heading thereof and inserting ``applicable asset loans''. (C) The following provisions of the Internal Revenue Code of 1986 are each amended by striking ``payments with respect to securities loans (as defined in section 512(a)(5))'' and inserting ``payments with respect to applicable asset loans (as defined in section 512(a)(5))'': (i) Section 509(e). (ii) Section 514(c)(8)(A). (iii) Section 851(b)(2)(A). (iv) Section 4940(c)(2). (D) Section 263(g)(2)(B)(iv) of such Code is amended by striking ``a payment with respect to a security loan (as defined in section 512(a)(5))'' and inserting ``a payment with respect to an applicable asset loan (as defined in section 512(a)(5))''. (d) Effective Date.-- (1) In general.--The amendments made by this section shall apply to transfers after the date of the enactment of this Act. (2) No inference.--The amendments made by this section shall not be construed to create any inference with respect to the non-recognition treatment of the transfer of any traded digital asset (within the meaning of section 1058(d) of the Internal Revenue Code of 1986, as added by this section) pursuant to an agreement that would otherwise qualify under 1058 of such Code before the date described in paragraph (1). SEC. 7. APPLICATION OF WASH SALE RULES TO DIGITAL ASSETS. (a) In General.--Section 1091 of the Internal Revenue Code of 1986 is amended-- (1) by striking ``stock or securities'' each place it appears and inserting ``specified assets'', and (2) by striking ``shares of'' each place it appears. (b) Specified Asset.--Section 1091 of such Code is amended by adding at the end the following new subsection: ``(g) Specified Asset.--For purposes of this section-- ``(1) In general.--The term `specified asset' means-- ``(A) any stock or security, and ``(B) any traded digital asset (other than a qualified U.S. dollar stablecoin). ``(2) Treatment of tokenized digital assets as substantially identical to an economically equivalent stock or security.--A tokenized digital asset (or a bridged digital asset with respect to which the reference digital asset is a traded digital asset) shall be treated as substantially identical to any stock, security, or traded digital asset if such tokenized digital asset (or such bridged digital asset) is economically equivalent to such stock, security, or traded digital asset.''. (c) Exception for Certain Acquisitions of Digital Assets.--Section 1091 of such Code, as amended by subsection (b), is further amended by adding at the end the following new subsection: ``(h) Exception for Certain Acquisitions of Digital Assets.--This section shall not apply with respect to the acquisition of a digital asset if such digital asset is acquired-- ``(1) in connection with the validation of digital asset transactions (including digital asset validation supporting activities), or ``(2) in a transaction which is part of a regular or periodic series of acquisitions of digital assets which are included by the taxpayer as ordinary income.''. (d) Exception for Certain Mark-to-Market Positions.--Section 1091 of such Code, as amended by subsections (b) and (c), is further amended by adding at the end the following new subsection: ``(i) Exception for Certain Mark-to-Market Positions.--This section shall not apply with respect to any specified asset to which subsection (a) of section 475 applies (including by reason of an election under subsection (e), (f), or (g) of such section).''. (e) Conforming Amendments.-- (1) Sections 312(f)(1) and 1256(f)(5) of the Internal Revenue Code of 1986 are each amended by striking ``stock or securities'' and inserting ``specified assets''. (2) Clause (ii) of section 6045(g)(2)(B) of such Code is amended to read as follows: ``(ii) Exception for wash sales.-- ``(I) In general.--Except as otherwise provided by the Secretary, the customer's adjusted basis shall be determined without regard to section 1091 (relating to loss from wash sales of specified assets) unless the transactions occur in the same account with respect to identical specified assets. ``(II) Tokenized digital assets.-- For purposes of subclause (I), a tokenized digital asset and a specified asset that is not a tokenized digital asset shall be treated as identical specified assets only if such tokenized digital asset is a direct digital representation of such other specified asset''. (3) Section 1091(e) of such Code (as amended by subsection (a)) is amended to read as follows: ``(e) Certain Short Sales of Specified Assets and Specified Asset Futures Contracts To Sell.--Rules similar to the rules of subsection (a) shall apply to any loss realized on the closing of a short sale of (or the sale, exchange, or termination of a specified asset futures contract to sell) specified assets if, within a period beginning 30 days before the date of such closing and ending 30 days after such date-- ``(1) substantially identical specified assets were sold, or ``(2) another short sale of (or specified asset futures contracts to sell) substantially identical specified assets was entered into. For purposes of this subsection, the term `specified asset futures contract' has the same meaning given the term `securities futures contract' under section 1234B(c), except that such term shall include a contract for the future delivery of a digital asset.''. (4) The heading of section 1091 of such Code is amended by striking ``stock or securities'' and inserting ``specified assets''. (5) The headings of subsections (b), (c), and (d) of section 1091 of such Code are each amended by striking ``Stock'' each place it appears and inserting ``Specified Assets''. (6) The item relating to section 1091 in the table of sections for part VII of subchapter O of chapter 1 of such Code is amended by striking ``stock or securities'' and inserting ``specified assets''. (f) Effective Dates.-- (1) In general.--Except as provided under paragraphs (2) and (3), the amendments made by this section shall apply to sales, dispositions, and terminations after the date of enactment of this Act. (2) Exception for certain acquisitions.--For purposes of the application of section 1091 of the Internal Revenue Code of 1986 with respect to any digital asset acquired before the date of enactment of this Act, the amendments made by this section shall be deemed to not apply. (3) Transition rule for broker reporting.--For purposes of the application of section 6045(g) of the Internal Revenue Code of 1986 with respect to any sales, dispositions, and terminations of any digital assets that are not securities before January 1, 2028, the amendments made by this section shall be deemed to not apply. SEC. 8. TREATMENT OF TRUSTS AND PUBLICLY TRADED PARTNERSHIPS HOLDING DIGITAL ASSETS. (a) Trusts.-- (1) In general.--Section 7701 of the Internal Revenue Code of 1986 is amended-- (A) by redesignating subsection (p) as subsection (q), and (B) by inserting after subsection (o) the following new subsection: ``(p) Tax Treatment of Certain Digital Asset Investment Trusts.-- ``(1) In general.--For purposes of this title, in the case of a covered digital asset investment trust formed to hold digital assets-- ``(A) any power held by the trustee to stake or unstake digital assets, whether directly or through delegation to another party, and to perform any related acts to exercise such power to stake, including the retention of staking rewards, shall not be treated as a power under such trust agreement to vary the investment of the certificate holders of such trust and shall not otherwise disqualify an entity from characterization as an investment trust that is not classified as a business entity under this section, ``(B) discretionary powers held by a trustee to use other measures, including a borrowing facility, to manage the trust's potential need for assets available to satisfy redemptions shall not be treated as a power under the applicable trust agreement to vary the investment of the certificate holders of such trust, and ``(C) discretionary powers held by a trustee to act in response to changes to technology supporting the digital assets held by the trust, including with regard to staking, shall not be treated as a power under the applicable trust agreement to vary the investment of the certificate holders of such trust. ``(2) Nonapplication to validating trade or business.--This subsection shall not apply in the case of any entity or arrangement engaged in the active conduct of a trade or business of validating digital asset transactions. ``(3) Covered digital asset investment trust.--For purposes of this subsection, the term `covered digital asset investment trust' means a trust which satisfies each of the following requirements: ``(A) The trust is traded on a national securities exchange which is registered with the Securities and Exchange Commission and complies with any applicable rules and regulations established by such Commission. ``(B) The trust only holds units of a single digital asset and any transactions with respect to such units are carried out on a network that uses a proof- of-stake consensus mechanism. ``(C) The trust's digital assets are held by a qualified custodian on behalf of the trust at digital asset addresses controlled by such custodian. ``(D) The trust directs staking of its digital assets through 1 or more custodians who facilitate the staking of the digital assets on behalf of the trust with 1 or more staking providers, subject to terms consistent with those that would be agreed to between unrelated persons dealing at arm's length under comparable circumstances. ``(4) Regulations and guidance.--The Secretary shall prescribe such regulations or other guidance as may be necessary and appropriate to carry out the purposes of this subsection''. (2) Effective date.-- (A) In general.--Subject to subparagraph (B), the amendments made by this subsection shall apply to taxable years beginning after December 31, 2026. (B) Election.--At the election of the taxpayer, the amendments made by this subsection may apply to any taxable years beginning before January 1, 2027. No inference may be drawn from the amendments made by this subsection with respect to the absence of explicit rules during such taxable years. (b) Publicly Traded Partnership.-- (1) In general.--Section 7704(d)(1) of the Internal Revenue Code of 1986 is amended-- (A) in subparagraph (F), by striking ``and'' at the end, (B) in subparagraph (G), by striking the period at the end and inserting ``, and'', (C) by inserting after subparagraph (G) the following new paragraph: ``(H)(i) staking rewards, to the extent includible in gross income, ``(ii) payments with respect to applicable asset loans (as defined in section 512(a)(5)) to the extent attributable to traded digital assets, or ``(iii) gains from the sale or exchange of-- ``(I) digital assets (other than those described in section 1221(a)(1) in the hands of the taxpayer), or ``(II) futures contracts, forward contracts, or options with respect to digital assets.'', and (D) in the flush text following subparagraph (H), by adding at the end the following: ``For purposes of subparagraph (H), qualifying income shall not include income or gain derived from operating a digital asset exchange, lending platform, broker, dealer, or other digital asset financial services business for a spread, commission, fee, or similar compensation.''. (2) Effective date.--The amendments made by this subsection shall apply to taxable years beginning after December 31, 2026. SEC. 9. APPLICATION OF CONSTRUCTIVE SALE RULES TO DIGITAL ASSETS. (a) In General.--Section 1259 of the Internal Revenue Code of 1986 is amended-- (1) in subsection (b)(1), by inserting ``digital asset (other than a qualified U.S. dollar stablecoin),'' after ``debt instrument,'', and (2) in subsection (c)-- (A) in paragraph (2), by inserting ``or widely traded digital asset'' after ``marketable security (as defined in section 453(f))'', and (B) by adding at the end the following new paragraph: ``(5) Treatment of tokenized digital assets as substantially identical to economically equivalent financial property.--A tokenized digital asset (or a bridged digital asset with respect to which the reference digital asset is a traded digital asset) shall be treated as substantially identical to any stock, debt instrument, partnership interest, or widely traded digital asset if such tokenized digital asset (or such bridged digital asset) is economically equivalent to such stock, debt instrument, partnership interest, or widely traded digital asset.''. (b) Effective Date.-- (1) In general.--The amendments made by this section shall apply to constructive sales after the date of enactment of this Act. (2) Rule of construction.--No transaction entered into on or before the date of enactment of this Act shall be deemed to cause or result in a constructive sale by reason of the amendments made by this section. SEC. 10. CHARITABLE CONTRIBUTIONS OF WIDELY TRADED DIGITAL ASSETS. (a) Exception From Appraisal Requirements.--Section 170(f)(11)(A)(ii)(I) of the Internal Revenue Code of 1986 is amended by inserting ``widely traded digital assets (except as the Secretary determines appropriate to prevent abuse of this section),'' after ``publicly traded securities (as defined in section 6050L(a)(2)(B)),''. (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2026. SEC. 11. TREATMENT OF DE MINIMIS DIGITAL ASSET NETWORK FEES. (a) In General.--Part III of subchapter O of chapter 1 of the Internal Revenue Code of 1986, as amended by section 2, is amended by inserting after section 1043 the following new section: ``SEC. 1044. DE MINIMIS NETWORK FEE EXCEPTION. ``(a) In General.--No gain or loss shall be recognized with respect to any qualified transaction cost disposition. ``(b) Qualified Transaction Cost Disposition.--For purposes of this section, the term `qualified transaction cost disposition' means the disposition of a digital asset by a taxpayer-- ``(1) in satisfaction of a digital asset transaction cost paid or incurred by the taxpayer, including a disposition resulting from the withholding of a digital asset from an amount transferred or received by the taxpayer, and ``(2) with respect to which the aggregate fair market value of all digital assets disposed of by the taxpayer in satisfaction of digital asset transaction costs relating to such transaction does not exceed $10. ``(c) Digital Asset Transaction Cost.-- ``(1) In general.--For purposes of this section, the term `digital asset transaction cost' means any amount paid in cash or property (including a digital asset) to effect the sale, disposition, or acquisition of a digital asset, including transaction fees, transfer taxes, commissions, and network fees paid or incurred with respect to any digital asset transaction initiated by the taxpayer and recorded on a cryptographically secured distributed ledger. ``(2) Network fee.--For purposes of paragraph (1), the term `network fee' means any amount paid or incurred to cause, facilitate, expedite, or prioritize the execution, validation, settlement, or recording of a digital asset transaction on a cryptographically secured distributed ledger or similar technology, including any base fee, gas fee, priority fee, tip, or similar amount, without regard to-- ``(A) whether payment of such amount is mandatory or elective, or ``(B) whether such amount is paid or transferred to a person, paid or transferred to a protocol, burned, destroyed, or otherwise removed from circulation. ``(d) Aggregation Rule.-- ``(1) In general.--For purposes of subsection (b)(2)-- ``(A) all digital assets disposed of in satisfaction of digital asset transaction costs relating to the same economic transaction shall be aggregated, including a series of related economic transactions structured for the purpose of avoiding the limitation under such subsection, and ``(B) any digital asset transaction cost paid or incurred to effect the disposition of a digital asset used to pay another digital asset transaction cost shall be treated as relating to the transaction to which such other cost relates. ``(2) Limitation.--For purposes of paragraph (1), transactions shall not be aggregated solely because such transactions are executed through the same account, wallet, protocol, program, smart contract, or automated strategy. ``(e) Determination of Fair Market Value.--For purposes of subsection (b)(2), the fair market value of a digital asset shall be determined as of the date and time of the disposition of such digital asset. ``(f) Coordination With Treatment of Transaction Costs.--Nothing in this section shall be deemed to modify the capitalization, allocation, or other treatment of a digital asset transaction cost. ``(g) Treatment of Unrecognized Gain.--The amount of any digital asset transaction cost which would otherwise be taken into account in determining the amount of gain or loss on the disposition of any asset, in determining the amount of any deduction, or in determining the basis of any asset acquired, shall be reduced by the amount of any gain or increased by the amount of any loss not recognized by reason of subsection (a) with respect to the disposition of the digital asset used to pay such digital asset transaction cost. ``(h) Exclusions.-- ``(1) Trade or business.--Subsection (a) shall not apply to the disposition of a digital asset by-- ``(A) a trader, broker, or dealer in digital assets, ``(B) a person in the trade or business of batching or facilitating the validation of digital asset transactions on behalf of others, ``(C) to the extent provided by the Secretary, any person in a trade or business which is substantially similar to a trade or business described in subparagraph (A) or (B), or ``(D) any person that initiated more than 5,000 digital asset transactions during the preceding taxable year. ``(2) Certain accounting methods.--Subsection (a) shall not apply to any digital asset-- ``(A) to which section 475 or 1256(a) applies, or ``(B) except as otherwise provided by the Secretary, to which a mark-to-market method applies under any other provision of this subtitle. ``(i) Regulations.--The Secretary shall issue such regulations or other guidance as may be necessary or appropriate to carry out the purposes of this section, including regulations or guidance to prevent the abuse of this section through transaction structuring for the purpose of qualifying for the exclusion provided in subsection (a).''. (b) Exemption From Information Reporting.--Section 6045(i) of such Code, as added by section 2 of this Act, is amended-- (1) by redesignating paragraph (2) as paragraph (3), and (2) by inserting after paragraph (1) the following new paragraph: ``(2) De minimis network fee exception.-- ``(A) In general.--Except as otherwise provided by the Secretary or under subparagraph (B), in the case of the disposition of a digital asset to which section 1044(a) applies, subsection (a) shall not apply with respect to such disposition. ``(B) Aggregate information.--With respect to any dispositions described in subparagraph (A), a broker shall include in the return under subsection (a) such aggregate information relating to such dispositions as the Secretary determines necessary or appropriate, including for purposes of verifying the taxpayer's basis in digital assets held by the taxpayer.''. (c) Exception From Wash Sale Rules.--Section 1091 of the Internal Revenue Code of 1986, as amended by this Act, is further amended by adding at the end the following new subsection: ``(j) Exception for Qualified Transaction Cost Dispositions.--This section shall not apply with respect to any qualified transaction cost disposition (as defined in section 1044(b)).''. (d) Clerical Amendment.--The table of sections for part III of subchapter O of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 1043 the following new item: ``Sec. 1044. De minimis network fee exception.''. (e) Effective Date.--The amendments made by this section shall apply to the disposition of assets after December 31, 2026. SEC. 12. TREATMENT OF INCOME FROM QUALIFIED DIGITAL ASSET VALIDATION ACTIVITY BY TAX-EXEMPT ENTITIES. (a) Treatment Under Unrelated Business Taxable Income.-- (1) In general.--Section 512(b) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph: ``(20) Certain digital asset validation income.-- ``(A) In general.--There shall be excluded income from qualified digital asset validation activity, and all deductions directly connected with such income. ``(B) Qualified digital asset validation activity.-- ``(i) In general.--For purposes of this subsection, the term `qualified digital asset validation activity' means any activity-- ``(I) which involves digital asset validation supporting activities, and ``(II) in which the taxpayer does not substantially participate. ``(ii) Substantial participation.--For purposes of clause (i)(II), a taxpayer shall be treated as not substantially participating in an activity described in clause (i)(I) if the taxpayer-- ``(I) owns the digital assets and delegates validation rights to another person on terms consistent with those that would be agreed to between unrelated persons dealing at arm's length under comparable circumstances, ``(II) does not operate the validator nodes and does not control validator selection beyond delegation and committing or uncommitting tokens to the validation network, and ``(III) does not undertake other activity that seeks to control the activity described in clause (i)(I).''. (2) Debt-financed property.--Section 512(b)(4) of such Code is amended by striking ``or (5)'' and inserting ``(5), or (20)''. (b) Regulations.--The Secretary of the Treasury (or the Secretary's delegate) shall issue such regulations or other guidance as may be necessary or appropriate to carry out the purposes of the amendments made by this section, including regulations or guidance to prevent the abuse of such amendments. (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2026. SEC. 13. APPLICATION OF REGISTRATION-REQUIRED OBLIGATION RULES. (a) Exception for Qualified U.S. Dollar Stablecoins.--Section 163(f)(2)(A) of the Internal Revenue Code of 1986 is amended-- (1) by striking ``or'' at the end of clause (ii), (2) by striking the period at the end of clause (iii) and inserting ``, or'', and (3) by adding at the end the following new clause: ``(iv) is a qualified U.S. dollar stablecoin.''. (b) Clarification of Treatment of Digital Assets.--Section 4701 of such Code is amended by adding at the end the following new subsection: ``(c) Digital Assets.-- ``(1) Location of disclosure statement.--In the case of any digital asset, the requirement of clause (iii) of subsection (b)(1)(B) shall be treated as satisfied if the statement described therein is included in all written terms or marketing materials with respect to such digital asset and in such other locations or documents as the Secretary may prescribe in regulations. ``(2) Treatment of digital assets without a fixed maturity date.--In the case of any digital asset that does not have a fixed maturity date at issue, the date of maturity of such asset for purposes of subsection (a)(2) shall be treated as the date that is 25 years after the date of issuance of such digital asset.''. (c) Effective Date.-- (1) In general.--Except as otherwise provided in this subsection, the amendments made by this section shall apply to taxable years ending after the date of enactment of this Act. (2) Clarification of treatment of digital assets without a fixed maturity date.--The amendment made by subsection (b) shall apply to digital assets issued after the date of enactment of this Act. SEC. 14. TREATMENT OF CERTAIN FOREIGN ENTITIES ESTABLISHED IN CONNECTION WITH DECENTRALIZED AUTONOMOUS ORGANIZATIONS. (a) In General.--Not later than12 months after the date of the enactment of this Act, the Secretary of the Treasury (or the Secretary's delegate) shall issue regulations or other guidance to clarify the appropriate tax treatment of reorganizations of applicable foreign entities (and United States persons related to such entities or involved in the governance of such entities). (b) Matters Included.--The regulations or other guidance issued under subsection (a) shall-- (1) clarify the methods by which applicable foreign entities may reorganize as domestic corporations under subchapter C of chapter 1 of the Internal Revenue Code of 1986, and (2) provide, in appropriate circumstances, temporary safe harbors to encourage applicable foreign entities organized before September 24, 2026, to complete such reorganizations promptly after the date of the enactment of this Act. (c) Applicable Foreign Entity.--For purposes of this section, the term ``applicable foreign entity'' means an entity which is established-- (1) in connection with an organization commonly referred to as decentralized autonomous organizations, and (2) in a foreign country as a foundation under foreign law (or other similar structure with a purported purpose other than profit). SEC. 15. DEFINITIONS. (a) In General.--Section 7701 of the Internal Revenue Code of 1986, as amended by section 8 of this Act, is further amended-- (1) by redesignating subsection (q) as subsection (r), and (2) by inserting after subsection (p) the following new subsection: ``(q) Definitions Related to Digital Assets.--For purposes of this title-- ``(1) Bridged digital asset.--Except as otherwise provided by the Secretary, the term `bridged digital asset' means any digital asset if such asset-- ``(A) is redeemable on demand, on a one-for-one basis, for another digital asset, and ``(B) is recorded on a cryptographically secured distributed ledger other than the cryptographically secured distributed ledger on which the digital asset referred to in subparagraph (A) is recorded. ``(2) Digital asset.--Except as otherwise provided by the Secretary, the term `digital asset' means any digital representation of value which is recorded on a cryptographically secured distributed ledger or any similar technology as specified by the Secretary. ``(3) Digital asset transaction.--The term `digital asset transaction' means any transaction, instruction, or other operation submitted for execution and recorded on the cryptographically secured distributed ledger (or similar technology) referred to in paragraph (2), regardless of whether such transaction, instruction, or other operation transfers a digital asset or is successfully executed. ``(4) Digital asset validation supporting activities.--The term `digital asset validation supporting activities' means staking, mining, or similar activities in support of the validation of digital asset transactions. ``(5) Mining.-- ``(A) In general.--The term `mining', when used in connection with a digital asset, means-- ``(i) performing computations, or making available computing power, in support of the validation of digital asset transactions on a cryptographically secured distributed ledger that uses a proof-of-work consensus mechanism, and ``(ii) except as otherwise provided by the Secretary, any activity which is substantially similar to an activity described in clause (i). ``(B) Exception.--The term `mining' does not include staking or the operation of a validator node on a cryptographically secured distributed ledger that uses a proof-of-stake consensus mechanism. ``(6) Qualified u.s. dollar stablecoin.-- ``(A) In general.--The term `qualified U.S. dollar stablecoin' means any U.S. dollar stablecoin which is issued by-- ``(i) a permitted payment stablecoin issuer (as defined in section 2(23) of the GENIUS Act, as in effect on the date of the enactment of this subsection), or ``(ii) a foreign payment stablecoin issuer (as defined in section 2(12) of the GENIUS Act, as so in effect) authorized to issue such U.S. dollar stablecoin to United States persons by reason of-- ``(I) registration with the Office of the Comptroller of the Currency under the GENIUS Act (as so in effect), or ``(II) a determination by the Secretary under such Act that the regulatory and supervisory regime of the jurisdiction in which such issuer is organized is comparable to the requirements of such Act. ``(B) Exception.--For purposes of subparagraph (A)(ii), a foreign payment stablecoin issuer shall not be treated as authorized to issue a U.S. dollar stablecoin under such subparagraph by reason of the absence of a prohibition on the offer or sale of such U.S. dollar stablecoin in the United States. ``(7) Receipt token.-- ``(A) In general.--Except as otherwise provided by the Secretary, the term `receipt token' means any digital asset (other than a bridged digital asset) that is readily redeemable, directly or through a protocol or similar arrangement, for a determinable amount of 1 or more other digital assets (referred to in this subsection as `underlying digital assets'), without regard to whether-- ``(i) such receipt token and any underlying digital asset are recorded on the same cryptographically secured distributed ledger, ``(ii) the amount of underlying digital assets for which such receipt token is redeemable varies over time, or ``(iii) redemption is subject to a waiting period, queue, or similar delay imposed by the protocol. ``(B) Tiered receipt tokens.--If any underlying digital asset with respect to a receipt token is itself a receipt token or a bridged digital asset-- ``(i) the underlying digital assets or reference digital asset of such asset shall be treated as underlying digital assets of the first receipt token, and ``(ii) rules similar to the rules of subparagraphs (B) and (C) of paragraph (8) shall apply. ``(8) Reference digital asset.-- ``(A) In general.--The term `reference digital asset' means, with respect to any bridged digital asset, the digital asset referred to in paragraph (1)(A). ``(B) Special rule for rewrappings.--If, but for this subparagraph, the reference digital asset with respect to any bridged digital asset would be a bridged digital asset (referred to in this paragraph as the `lower-tier bridged digital asset')-- ``(i) subparagraph (A) shall be applied with respect to the lower-tier bridged digital asset, and ``(ii) the reference digital asset with respect to such lower-tier bridged digital asset shall be treated as the reference digital asset of such bridged digital asset. ``(C) Multiple wrappings.--If, after the application of subparagraph (B), the reference digital asset with respect to the lower-tier bridged digital asset is a bridged digital asset, such subparagraph shall be reapplied by treating such lower-tier bridged digital asset as the bridged digital asset. ``(9) Staking.--The term `staking', when used in connection with a digital asset, means-- ``(A) making such asset available in support of the validation of digital asset transactions, and ``(B) to the extent provided by the Secretary, any activity which is substantially similar to an activity described in subparagraph (A). ``(10) Staking reward.-- ``(A) In general.--The term `staking reward' means any additional units of a digital asset, or portions thereof, that are created or issued by the protocol itself as part of validation and allocated to a taxpayer (directly or through 1 or more agents or pools) as a result of the taxpayer's direct or indirect participation in digital asset validation supporting activities of a distributed ledger. ``(B) Exclusion for service compensation.-- ``(i) In general.--The term `staking reward' shall not include any fee, commission, spread, or other amount received for providing validation, staking, exchange, lending, or other digital asset financial services to another person. ``(ii) Exception.--For purposes of clause (i), a protocol-issued reward shall not be treated as compensation for providing digital asset financial services merely because the taxpayer directly validates transactions or delegates digital assets to a validator. ``(11) Tokenized digital asset.--The term `tokenized digital asset' means any digital asset (other than a qualified U.S. dollar stablecoin) that is a digital representation of all rights, obligations, or interests in a tangible or intangible asset that is not itself a digital asset. ``(12) Traded digital asset.--Except as otherwise provided by the Secretary, the term `traded digital asset' means any digital asset if-- ``(A) such asset is fungible, ``(B) quotations of such asset are readily available or readily ascertainable on 1 or more exchanges and reflect trading in sufficient volume and with sufficient liquidity to provide reliable price discovery, and ``(C) such asset is either-- ``(i) not a tokenized digital asset, ``(ii) a bridged digital asset with respect to which the reference digital asset is a traded digital asset, or ``(iii) a receipt token with respect to which each underlying digital asset is a traded digital asset. ``(13) U.S. dollar stablecoin.--The term `U.S. dollar stablecoin' means a payment stablecoin as defined in section 2(22) of the GENIUS Act (as in effect on the date of the enactment of this subsection) applied by substituting `dollars' for `monetary value' each place it appears in such section. ``(14) Validation.--The term `validate', and any derivative of such term (including `validation'), when used in connection with a digital asset transaction, means participating in a consensus process of a cryptographically secured distributed ledger by proposing, attesting to, verifying, ordering, recording, or otherwise confirming transactions or blocks. ``(15) Widely traded digital asset.-- ``(A) In general.--Except as otherwise provided by the Secretary, the term `widely traded digital asset' means, for any taxable year, any traded digital asset if-- ``(i) quotations for such asset were readily available on an exchange for the entirety of the immediately preceding calendar year, ``(ii) the market capitalization of such asset exceeded $500,000,000 at substantially all times during such calendar year, and ``(iii) not more than 10 percent of the units of such asset were owned, directly or indirectly, by the taxpayer or any person described with respect to the taxpayer under section 267(b) (applied without regard to section 267(c)(3)) or section 707(b)(1) at any time during such taxable year or the immediately preceding taxable year. ``(B) Special rule for bridged digital assets.-- Except as otherwise provided by the Secretary, in the case of any bridged digital asset, such asset shall be treated as a widely traded digital asset if the reference digital asset with respect to such bridged digital asset is a widely traded digital asset. ``(C) Authority to ensure reliable price discovery.--For purposes of subparagraphs (A) and (B), the Secretary may exclude any asset that lacks reliable price discovery or that the Secretary determines is at risk of price manipulation. ``(D) Authority to adjust requirements.--The Secretary may, by regulation, provide requirements that apply in lieu of 1 or more of the requirements of clauses (i) through (iii) of subparagraph (A) if the Secretary determines that, due to changes in market conditions (including by reason of the enactment of Federal legislation relating to digital asset market structure), such alternative requirements would more effectively or efficiently identify traded digital assets for which there is consistent and reliable price discovery. ``(E) Special rule for receipt tokens.--Except as otherwise provided by the Secretary, a receipt token shall be treated as a widely traded digital asset if each underlying digital asset with respect to such receipt token is a widely traded digital asset. ``(F) Inflation adjustment.--In the case of any calendar year after 2027, the $500,000,000 amount in subparagraph (A)(ii) shall be increased by an amount equal to-- ``(i) such dollar amount, multiplied by ``(ii) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year, determined by substituting `calendar year 2026' for `calendar year 2016' in subparagraph (A)(ii) thereof. Any increase determined under the preceding sentence which is not a multiple of $100,000 shall be rounded to the nearest multiple of $100,000.''. (b) Conforming Amendments.-- (1) Section 6045(g)(3) of the Internal Revenue Code of 1986 is amended by striking subparagraph (D). (2) Section 6050I(d)(3) of such Code is amended by striking ``(as defined in section 6045(g)(3)(D))''. <all>
Related legislation
Bills by the same sponsor or covering overlapping subjects.
- S240Crow Tribe Water Rights Settlement Amendments Act of 2025Passed Both Chambers · 2026-10-05
- S239Crow Revenue ActReported by Committee · 2026-09-28
- S4041Cooperative Watershed Management Program Reauthorization Act of 2026Reported by Committee · 2026-09-17
- SRES816A resolution honoring 35 years of independence for the countries of Central Asia and recognizing the importance of the United States growing relationship with Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, and Uzbekistan.Referred to Committee · 2026-09-17